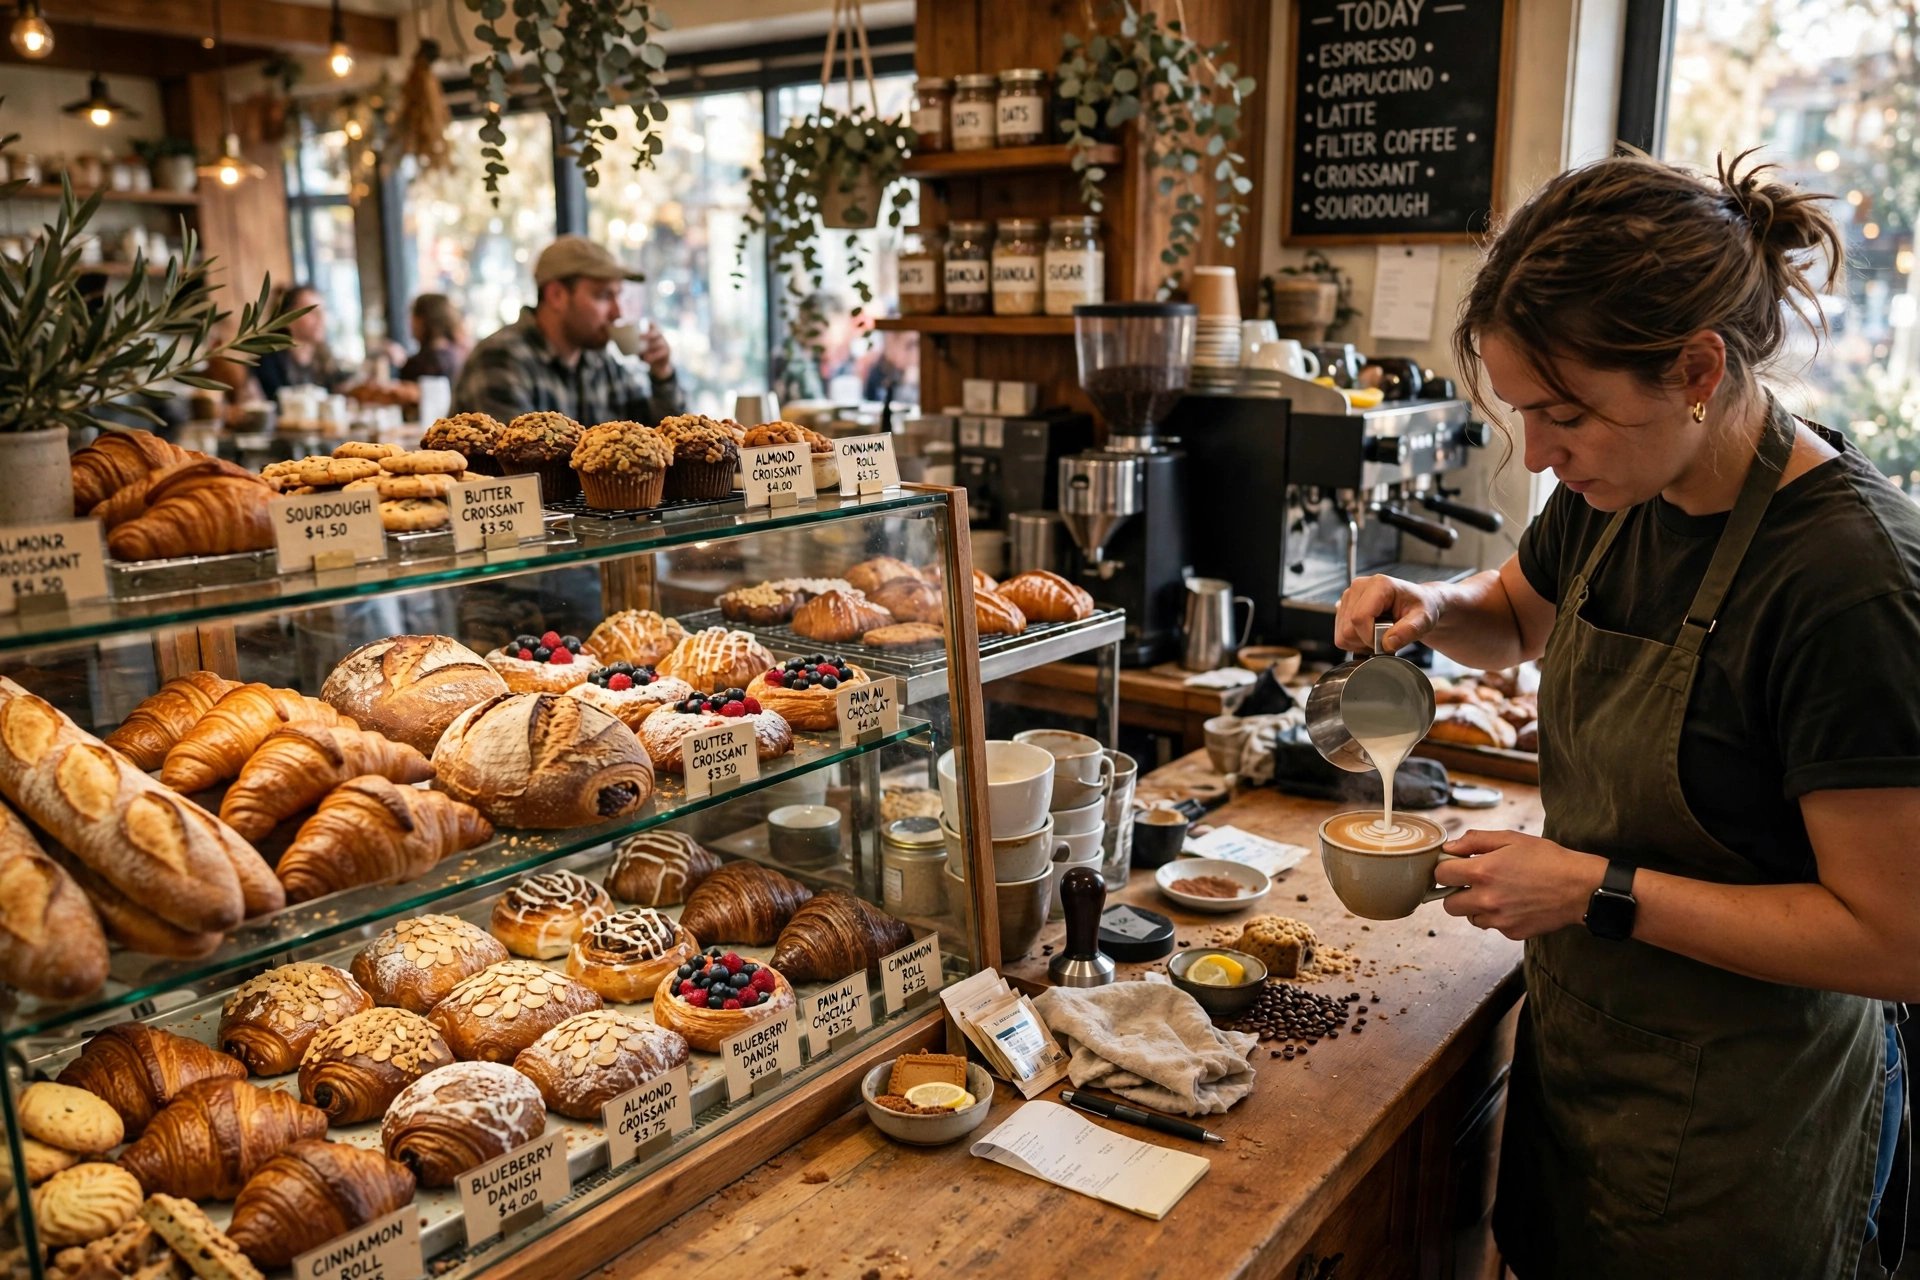
Bakeries and cafes run on thin margins, early mornings, and equipment that cannot fail during the morning rush. A deck oven down on a Saturday, a walk-in that quits before a holiday weekend, a landlord offering the space next door — every one of these is a funding decision with a clock on it. This guide covers what bakery and cafe owners actually borrow for, which product fits each need, and what funders weigh on a food-business file.
The food business is capital-hungry in a specific way: the expensive stuff (ovens, mixers, espresso machines, build-outs) is bought up front, while the revenue arrives $4 and $6 at a time. That mismatch is why bakeries and cafes borrow more often than most small businesses — and why matching the product to the purchase matters more than the headline rate.
What bakeries and cafes borrow for
Equipment. A commercial deck oven, a spiral mixer, a dough sheeter, or a two-group espresso machine are the classic equipment-financing purchases: named assets with vendor quotes and long useful lives. Equipment financing typically matches payments to the gear's life, and the equipment itself secures the loan — which is why it is usually the cheapest money a bakery can get.
Build-outs and second locations. Leasehold improvements, seating, signage, and a second oven line for a wholesale account. These are term-loan or SBA territory when the timeline allows, because the amounts are larger and the payoff stretches over years, not months.
Seasonal inventory and staffing. Holiday baking season, wedding season, and summer patio traffic all demand buying ingredients and hiring weeks before the revenue lands. A line of credit drawn for the season and repaid after it fits this pattern far better than a fixed-payment loan.
Emergencies. The oven that dies mid-week, the refrigeration failure that costs a full case of product, the health-department fix that cannot wait. This is where revenue-based funding earns its keep: fast money for a problem that is already costing you sales.
Which product fits which bakery need
| Need | Best fit | Why |
|---|---|---|
| New oven, mixer, espresso machine | Equipment financing | Asset secures the loan; payments matched to equipment life |
| Build-out or second location | Term loan or SBA loan | Larger amounts, longer payoff, lower cost when time allows |
| Holiday / seasonal ingredient buys | Business line of credit | Draw, repay, redraw as seasons turn |
| Emergency repair or same-week gap | Merchant cash advance | Decision in hours, funding in 24–72 hours |
| Slow-paying wholesale accounts | Invoice factoring | Advances against outstanding invoices, not new debt |
What funders actually weigh on a bakery or cafe file
Bank deposits, not the menu. Funders underwrite on the last 3 months of bank statements: average monthly deposits, deposit frequency, and whether balances stay positive. A cafe doing steady card volume with a clean deposit record is a fundable file even with a modest credit score.
Food costs and margins. Expect questions about ingredient costs as a share of sales. A bakery running food costs far above its category norm is a risk flag — not because funders are chefs, but because the margin left after ingredients is what services the debt.
Lease terms. Time left on the lease matters, especially for build-out funding. A funder financing a $60,000 build-out wants to know the business will still be in the space long enough to earn it back.
Seasonality, honestly stated. A bakery that does 40% of annual revenue between Thanksgiving and Christmas is not a weak file — it is a seasonal file. Funders would rather see the pattern named and planned for than discover it in the statements.
The documents: short list, no surprises
- Last 3 months of business bank statements — the one document every funder requires
- Vendor quotes for any equipment being financed
- Lease copy, for build-out or expansion funding
- Photo ID and a voided check available if a specific product's verification asks — neither is required upfront to see offers
Mistakes that cost bakery owners real money
Funding a 10-year oven with a 6-month advance. Daily-debit products are for short gaps, not long-lived assets. Match the payoff to the purchase, or the payments eat the margin the oven was supposed to create.
Ignoring the wholesale trap. A grocery or coffee-shop wholesale account looks like growth until net-30 terms mean you fund their shelves for a month. Factor those invoices or price the terms in — don't carry them on an advance.
Waiting until the equipment fails. Emergency money is always the most expensive money. An oven showing its age is a planned purchase; the same oven dead on a Friday is an emergency.
Frequently asked questions
Can a bakery with bad credit get a business loan?
Yes. Revenue-based funders weight bank deposits far more heavily than credit score, and scores in the 500s routinely get funded on bakery files. Credit affects the cost of the offer, not usually the yes-or-no.
How much can a bakery or cafe borrow?
Offers generally scale with monthly revenue: revenue-based products commonly run from a fraction of one month's deposits up to several months' worth, depending on deposit consistency and existing obligations. The honest answer comes from your statements, not a calculator.
What is the cheapest way to finance bakery equipment?
Equipment financing, in most cases — the equipment secures the loan, which lowers the funder's risk and your cost. SBA loans are cheaper still for large build-outs, but take 30–90 days to close.
Do I need a voided check or photo ID to apply?
No — not to see offers. Bank statements and an application are the standard ask. A voided check or photo ID is sometimes requested for verification on specific products before funding, but neither is a universal upfront requirement.
How fast can a cafe get funded?
Revenue-based products decide in hours and fund in 24–72 hours once statements are in. Term loans and lines of credit take days to a couple of weeks; SBA products take a month or more.
Should a bakery take an MCA for a holiday inventory buy?
Only if the math works: the margin on the holiday sales must comfortably exceed the total repayment cost. For recurring seasonal buys, a line of credit you repay after the season is almost always the cheaper structure.
Oven down, build-out planned, or holiday season coming? See what you qualify for
From the next deck oven to the holiday ingredient buy — get a no-obligation quote from our #1-ranked lender, Coast to Coast Fast Funding. One application reaches multiple funders, so you see the actual market for your file.
Apply Now →Soft credit check · 60-second pre-qualification