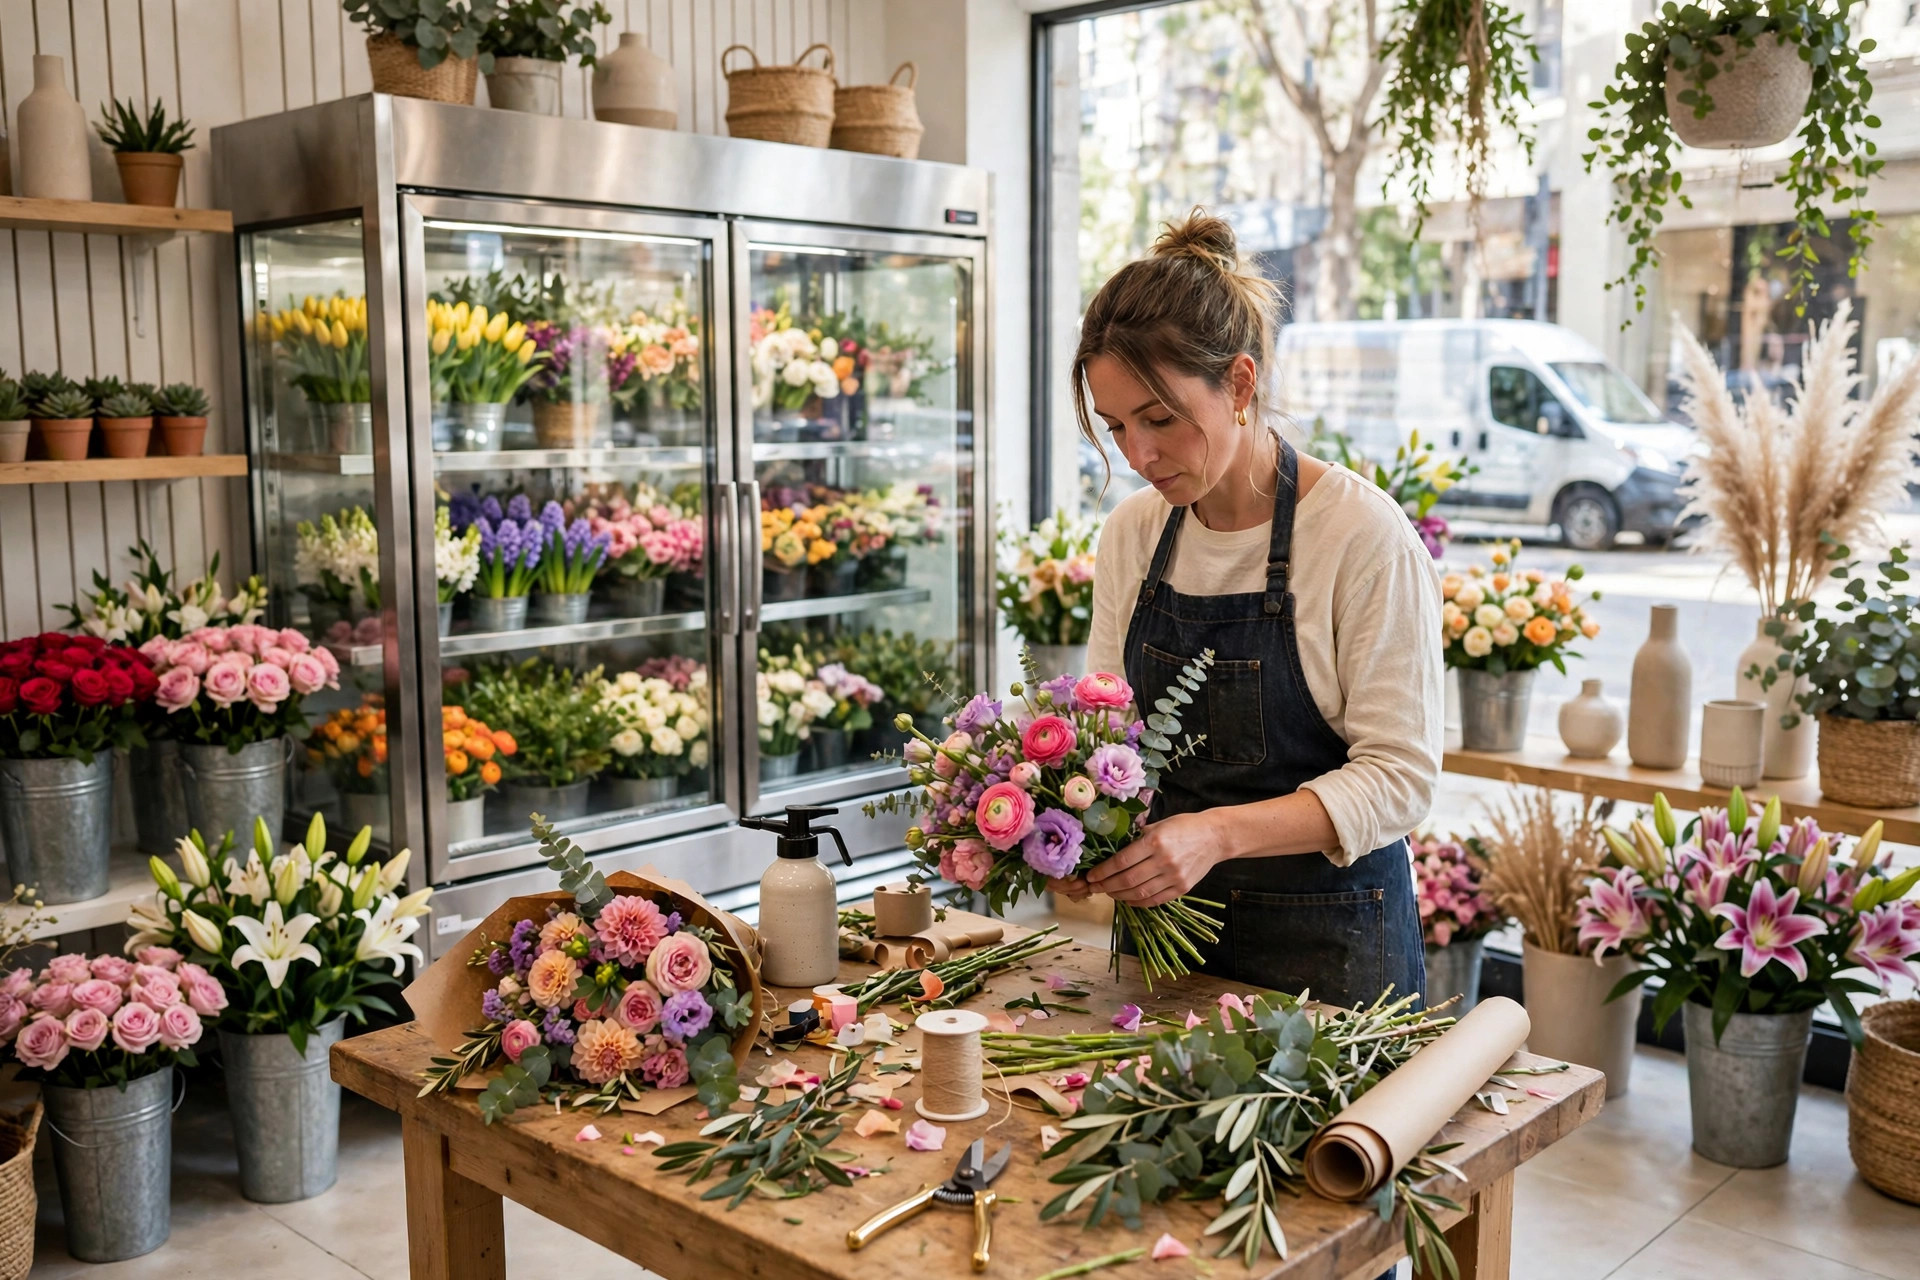
Flower shops look simple from the sidewalk — buckets of color, a cooler humming in the back, a delivery van at the curb — but the business underneath is one of the most cash-flow-sensitive in retail. The inventory dies in days, the year's revenue arrives in a handful of holiday spikes, and the wholesale flowers for Valentine's Day have to be paid for weeks before the orders land. This guide covers what florists actually borrow for, what opening, buying, or upgrading a shop costs in 2026, and which product fits each need.
The funding map for a flower shop splits into five buckets: opening a new shop, buying an existing one, upgrading refrigeration and delivery, pre-buying holiday inventory, and funding the working-capital gap behind weddings and corporate accounts. Each bucket has a different best product, and the single most important underwriting fact in all five is seasonality: a florist's year is not twelve equal months, and any funder who averages it flat will misprice the file.
What florists borrow for
Opening a new shop. The most common first funding need, and the one with the widest cost range. A modest neighborhood shop can open in the $15,000 to $100,000 range in published planning guides, with refrigeration and build-out the biggest swing factor. The money goes to the cooler, the first inventory, the delivery vehicle, and the operating reserve for the months before the shop finds its rhythm — most guides say 6 to 18 months to consistent profitability.
Buying an existing shop. Acquisitions are common and often smarter: the shop comes with a customer list, standing funeral-home and corporate accounts, a wire-service membership, and a cooler already installed. Funding is usually an SBA loan or a term loan underwritten on the shop's historical cash flow — and on the accounts: a shop with standing weekly corporate orders and a wedding book is worth materially more than one living on walk-in traffic alone.
Upgrading refrigeration and delivery. The classic florist investment. A walk-in cooler plus display coolers runs $4,000 to $18,000, and a refrigerated delivery setup runs $5,000 to $20,000 or more. The cooler is not cosmetic: fresh flowers lose value every day, and published guides put perishable waste at 8 to 15 percent of stock per week. A shop that tracks shrinkage weekly holds the high end of the industry's 8 to 12 percent net margin; one that estimates it does not.
Pre-buying holiday inventory. The working-capital crunch unique to florists. Valentine's Day and Mother's Day alone can account for 25 to 35 percent of a shop's annual revenue inside roughly a ten-day combined window — but the wholesale stock for those peaks has to be ordered and pre-paid weeks earlier. A short revenue-based advance or a line of credit that bridges the pre-buy to the holiday weekend is the most financeable project in the industry, because the repayment source is dated and visible.
Wedding, event, and corporate working capital. Event work pays a deposit up front and the balance on or after the event date, while the flowers, vases, foam, and delivery help are all bought before it. Hotel, restaurant, and office accounts often pay on net-30 or net-45 terms, so a standing weekly arrangement order can sit as a receivable for six weeks. A line of credit that floats those receivables is the right product; a daily-debit advance sized to a holiday peak is not.
What a flower shop actually costs in 2026
| Cost item | Published 2026 planning range | What drives it |
|---|---|---|
| Walk-in cooler plus display coolers | $4,000–$18,000 | Size, new vs. used, temperature-control quality |
| Opening inventory (flowers, greenery, containers, supplies) | $3,000–$8,000 | Shop size, opening week order volume |
| Ongoing weekly flower purchases | $1,500–$4,000 | Sales volume, variety carried, season |
| Delivery vehicle (used van, climate-appropriate) | $5,000–$20,000+ | Refrigeration, vehicle age, wrap/lettering |
| Wire-service membership (FTD, Teleflora) | Membership fee plus 20–27% of routed orders | Order volume routed through the network |
| Monthly operating expenses (rent, labor, inventory, delivery) | $14,000–$33,000 | Location, staff count, delivery volume |
| Working-capital reserve (6 months of operating expenses) | $60,000–$100,000 typical | Market, rent, time to profitability |
| Total to open a modest independent shop | $30,000–$100,000 | Published guide range; premium locations run higher |
These are planning ranges from published guides, not lender terms or quotes. Two notes matter for funding: no US state currently requires an occupational floristry license — the general business license, sales tax permit, and liability insurance are the standard paperwork, which keeps the opening timeline short — and the cooler decision is a financial decision, not a cosmetic one, because every point of waste avoided drops straight to the bottom line.
How a flower shop actually makes money
Funders underwrite a flower shop on three revenue layers, and the mix between them changes the file's risk profile.
Holiday peaks. Valentine's Day, Easter, Mother's Day, Thanksgiving, and the run to Christmas carry the year. A shop that plans its pre-buy, staffing, and delivery capacity around those dates — and can show last year's peak deposits — underwrites better than one that treats every month as average, because the funder can see exactly when repayment cash arrives.
Weddings and events. The highest-margin layer: custom designs, large orders, and a book that can be sold months ahead. The risk is timing — deposits up front, balances after the event — so funders discount event revenue that is booked but not yet collected, and they reward shops whose books show deposits already banked.
Standing accounts and wire orders. The stability layer: funeral homes, hotels, restaurants, and offices on weekly standing orders, plus wire-service orders routed from other shops. Standing accounts pay on terms, which creates receivables, but they also prove the shop is embedded in its market — and wire orders, even after the network's 20 to 27 percent commission, fill otherwise idle design hours.
The cost side is dominated by perishability. Flowers are bought weekly, priced by season, and wasted at 8 to 15 percent a week if buying and cooler discipline slip. A cold snap or a shipping delay at a major import hub can push a stem price up overnight — which is why the shops that hold margin are the ones that track waste weekly, buy to the book, and never let the cooler become a guessing game.
Which product fits which florist need
| Your need | Best first product | Why |
|---|---|---|
| Open a new flower shop | SBA 7(a) loan or term loan | Long term for a build-out with a slow ramp to profitability |
| Buy an existing shop | SBA 7(a) loan | Underwritten on the shop's historical cash flow and standing accounts |
| Cooler, display cases, or delivery vehicle | Equipment financing | The asset secures the loan; term matches equipment life |
| Pre-buy Valentine's or Mother's Day inventory | Revenue-based funding or line of credit | Bridge a dated, visible repayment source — sized to the peak |
| Float wedding balances and net-30 corporate accounts | Line of credit | Draw only what the receivables gap requires |
| Bridge a slow month or an emergency repair | Revenue-based funding or line of credit | Funds in days — sized small, for a short gap only |
Opening, buying, or upgrading a flower shop? See what you qualify for
From the first cooler to the Valentine's pre-buy — get a no-obligation quote from our #1-ranked lender, Coast to Coast Fast Funding. One application reaches multiple funders, so you see the actual market for your file.
Apply Now →Soft credit check · 60-second pre-qualification